Business
Japan’s Economy Contracts as U.S. Tariffs Hit Exports, Posing Early Test for New Prime Minister

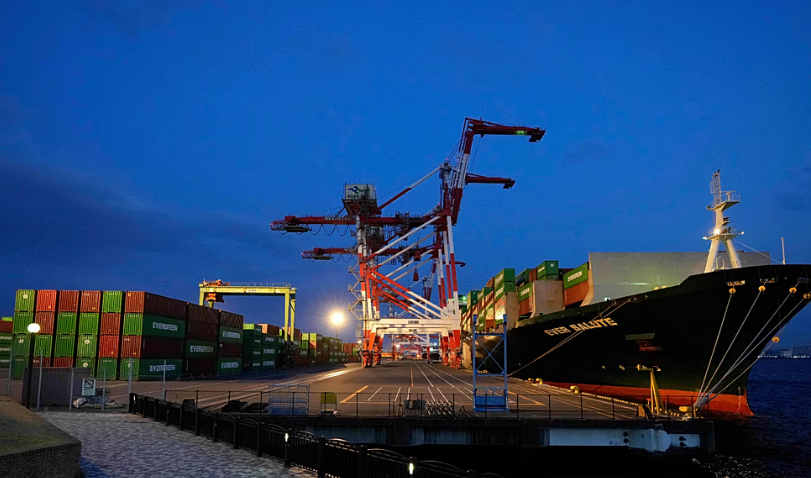
Japan’s economy recorded a sharp slowdown in the July–September quarter, contracting for the first time in a year and a half as U.S. trade tariffs weighed heavily on exports. Government figures released on Monday showed an annualised decline of 1.8%, driven largely by weakened overseas demand after Washington imposed new duties on Japanese goods.
While the downturn was significant, it was not as steep as the 2.6% drop projected by economists. On a quarter-to-quarter basis, gross domestic product slipped 0.4%, ending six straight quarters of expansion and signalling a tougher economic landscape for recently appointed Prime Minister Sanae Takaichi.
Exports recorded one of the sharpest declines of the quarter, falling 1.2% from the previous period. The government noted that some firms rushed shipments earlier in the year to get ahead of tariff deadlines, which boosted earlier export data but resulted in weaker numbers for the autumn quarter. On an annualised basis, exports tumbled 4.5%.
Imports were slightly lower as well, dipping 0.1%, while private consumption — a key driver of the domestic economy — inched up by the same margin. Economists say the modest rise in household spending is not enough to offset the strain placed on the country’s major industries.
The tariff pressures stem from measures introduced by U.S. President Donald Trump, who has implemented a 15% duty on nearly all Japanese imports. Although this marks a reduction from the previous 25% rate, the impact has been severe for Japan’s export-heavy economy. Automakers such as Toyota Motor Corp. have long been central to Japan’s global trade profile, though many have built factories abroad to reduce exposure to such trade barriers.
The latest GDP results add to the mounting challenges facing Takaichi, who assumed office in October. Alongside the economic risks, her government is navigating rising diplomatic tensions with China. Earlier this month, the prime minister stated that Japan may consider military action if Beijing launches an attack on Taiwan, prompting sharp reactions from Chinese officials.
Talks between diplomats from both countries are scheduled to take place on Tuesday, with economic stability and regional security expected to dominate the agenda.
The combination of trade pressures, geopolitical strain and a fragile domestic recovery places Japan at a sensitive moment, with policymakers now under heightened pressure to stabilise growth in the months ahead.



European shares opened sharply lower on Friday as a heavy sell-off in US technology stocks spread across global markets, with investors concerned that political opposition to artificial intelligence data centres could slow the industry’s expansion.
The S&P 500 companies lost a record $2.9 trillion in market value on Thursday. In early European trading, the Stoxx Europe 600 fell 1.2%, Germany’s DAX dropped 1.6%, while France’s CAC 40 and London’s FTSE 100 each declined 1.4%.
The MSCI AC Asia Index fell more than 4% as investors sold AI-related and semiconductor shares. However, US futures pointed to a possible pause, with Nasdaq-100 futures rising 1.5% at around 10:15 CET.
Markets were assessing whether sweeping Democratic victories in this week’s US midterm elections could result in tighter restrictions on data centre construction. Opposition to the projects has grown across political lines, with several successful candidates pledging to slow or stop new developments.
Market intelligence firm Cleanview estimates that about 40% of planned US data centre capacity is located in states where governors or governors-elect have pledged or already introduced pauses on new projects. Senator Bernie Sanders and Representative Alexandria Ocasio-Cortez also proposed a federal moratorium earlier this year.
The uncertainty has raised questions about whether technology companies will earn sufficient returns on the hundreds of billions of dollars invested in AI infrastructure. Higher borrowing costs could also make construction more expensive, potentially reducing demand for chips and electricity.
Chipmakers lead global market declines
The Philadelphia Semiconductor Index plunged 12.2% on Thursday, marking its largest one-day fall since 2020. The index was down around 16% for the week through the close.
The Nasdaq Composite lost 5.5%, the S&P 500 fell 4.4% and the Dow Jones Industrial Average declined 3.4%. All three recorded their steepest daily percentage losses since US President Donald Trump announced sweeping tariffs in April 2025.
Stuart Clark, a portfolio manager at Quilter, said the declines highlighted the dependence of major US stock indices on a relatively small number of large technology and semiconductor companies.
The sell-off also reduced the fortunes of prominent technology executives. Nvidia chief executive Jensen Huang’s net worth fell by $15.1 billion, while Elon Musk’s dropped by $79.7 billion, according to the Bloomberg Billionaires Index.
Asian chipmakers also suffered heavy losses. Japan’s Nikkei 225 closed 6% lower, while South Korea’s Kospi fell 6% after an earlier decline of as much as 8.8% triggered a 20-minute trading halt. SK Hynix shares dropped 10.4% and Samsung Electronics lost 6.4%.
Taiwan’s Taiex finished 4.5% lower, with TSMC shares down 4.7%. Hong Kong’s Hang Seng was about 1.1% lower at the midday break, while Shanghai’s Composite declined 1.1%.
Neil Wilson of Saxo Markets described the sell-off as potentially excessive but said investors would first want to see markets stabilise.
Elsewhere, Bloomberg reported that Dutch bank ING was seeking to sell a portfolio of data centre loans worth about $500 million. Brent crude traded just below $99 a barrel, while government bonds gained as investors sought safer assets. The US 10-year Treasury yield fell six basis points to 4.84%, and the euro slipped 0.3% against the dollar to $1.1188.
BMW reported a decline in third-quarter profits on Wednesday, a day after issuing its second profit warning of the year as mounting competition from Chinese carmakers and restructuring costs put pressure on the German manufacturer’s business.
The company’s pre-tax profit fell 11% in the three months to September, while net profit dropped around 15% to €1.45 billion. Revenue declined almost 6% to €30.45 billion, BMW said.
The latest warning, announced on Tuesday, followed higher restructuring expenses, including the planned elimination of around 8,000 jobs in Germany. BMW said these costs could push its core automotive division close to break-even, or into an operating loss, for the full year.
The operating margin in the car division fell to 3.4% in the third quarter, compared with 5.2% in the same period last year. BMW now expects the division’s full-year operating margin to range between minus 0.5% and plus 0.5%, a sharp reduction from its previous forecast of 1% to 3%.
BMW chief executive Milan Nedeljkovic said the company needed to respond quickly to changes across the automotive industry.
“Current developments in our industry call for decisiveness and swift implementation,” he said. “We will therefore specifically intensify and accelerate structural measures.”
The pressure reflects wider challenges facing German manufacturers, including Mercedes-Benz and Volkswagen, which are also reducing costs and jobs. Chinese carmakers have gained ground in their domestic market with competitively priced vehicles and advanced technology, while expanding their presence in Europe.
BMW’s difficulties have been particularly pronounced in China, traditionally one of its most important markets. Vehicle deliveries there fell 24.8% in the third quarter, extending a decline that has already taken sales to their lowest level since 2017 last year.
The drop in China contributed to a 6.3% decline in BMW’s global deliveries during the quarter. Sales moved in the opposite direction in other major markets, rising 2.6% in Europe and 2.5% in the United States.
The group, which owns the BMW, Mini and Rolls-Royce brands, is seeking to regain ground in China by shifting more of the supply chain for vehicles made there to local suppliers. The strategy is intended to improve competitiveness and respond more closely to customer demand in the market.
The latest results add to concerns about the outlook for Germany’s automotive industry, which faces pressure from weaker demand, high production costs and the rapid expansion of Chinese competitors.
Despite the profit warning and weaker quarterly performance, BMW shares rose around 2% from Tuesday’s closing level by 11 a.m. Central European Time on Wednesday.
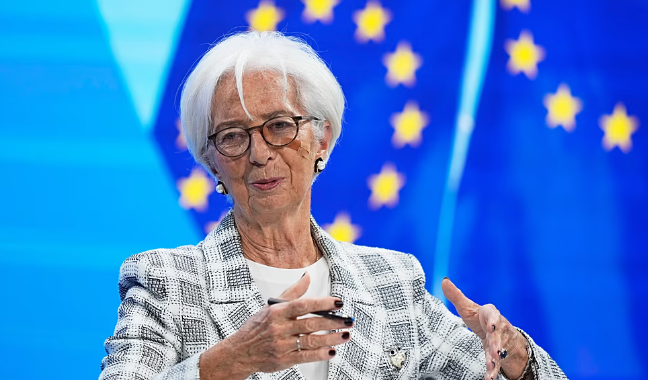
Eurozone governments have until Friday, 6 November, to nominate candidates to succeed European Central Bank (ECB) President Christine Lagarde, with finance ministers scheduled to review the submissions at a meeting on 9 November.
The appointment process began after Lagarde informed European Council President António Costa last week that she intended to leave the post on 7 February 2027, almost nine months before the end of her eight-year term.
A Eurogroup spokesperson told Euronews that the Council of the European Union had initiated the procedure to appoint her successor. The ECB Executive Board is appointed by the European Council, which makes its decision based on a recommendation from the Council of the EU.
Eurogroup President and Greek Finance Minister Kyriakos Pierrakakis has asked eurozone members to submit nominations by Friday. The Eurogroup will then assess the candidates at its 9 November meeting.
A nominee must secure support from at least 16 of the 21 eurozone countries, representing at least 65 per cent of the bloc’s population. EU leaders will make the final appointment after receiving opinions from the European Parliament and the ECB’s Governing Council.
Lagarde announced her early departure last Thursday, saying she wanted greater freedom to speak about issues beyond monetary policy.
“I don’t think that I can remain neutral,” she told reporters in Frankfurt. “I’m interested in the truth, and I see the truth being very often damaged, contradicted by misrepresentation.”
She did not say whether she would support a candidate in France’s presidential election in April 2027. Her decision to leave early has fuelled speculation about the timing of the succession, allowing French President Emmanuel Macron and German Chancellor Friedrich Merz to influence the appointment before the election.
Lagarde has promised continuity at the central bank and is expected to chair two more interest-rate meetings, in December and February. The ECB kept its deposit rate at 2.5 per cent at its latest meeting.
Two candidates have emerged as leading contenders. Spain has backed Pablo Hernández de Cos, general manager of the Bank for International Settlements and former governor of the Bank of Spain. Prime Minister Pedro Sánchez publicly endorsed him in September, while opposition leader Alberto Núñez Feijóo has also expressed support.
The Netherlands has backed former central bank governor Klaas Knot, who led the institution for 14 years until 2025. Prime Minister Rob Jetten described him as a “perfect fit” for many countries.
Other names mentioned in the race include former Bank of France governor François Villeroy de Galhau and Bundesbank President Joachim Nagel.
The negotiations are expected to extend beyond the presidency. ECB Executive Board positions held by Germany’s Isabel Schnabel and Ireland’s chief economist Philip Lane are also due to become vacant in the coming months. With several senior posts changing hands, governments are expected to negotiate over the appointments as part of a wider package.

Global Stock Sell-Off Deepens as AI Data Centre Concerns Hit Chipmakers

Big Tech Firms and Environmental Groups Join Forces to Set Data Centre Guidelines

Parents Sue Google Over AI Search After Teen Allegedly Used It to Plan Suicide

Experts Call for Stricter Fireworks Rules as Injuries Rise Across Europe

European Campaigners Demand Pause on Large Data Centre Projects Amid Growing Local Opposition

One in Four Teenagers Worldwide Does No Weekly Exercise, Study Finds

US Midterm Results Put Data Centre Expansion Under Pressure as Democrats Win Key States

BMW Profits Fall as Chinese Competition Forces Deeper Cost Cuts

Eurozone Opens Race to Replace ECB President Christine Lagarde

Health Groups Urge WHO to Tighten Drinking Water Nitrate Limits Over Cancer Risks

Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’

China’s Historic Olympic Victory Sparks National Pride Amid Controversy

Saudi Arabia’s Model for Sustainable Aviation Practices

Recent Developments in Small Business Taxes

Effective Drain Cleaning: A Key to a Healthy Plumbing System

Who was Ebrahim Raisi and his status in Iranian Politics?

Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m

Carrectly: Revolutionizing Car Care in Chicago

Nobel Laureate Muhammad Yunus Proposed as Head of Bangladesh’s Interim Government Following Hasina’s Resignation

Chinese Hackers Infiltrate Major U.S. Telecom Firms in Possible National Security Breach
Sony WF-10XM4: Headphones Are Our Absolute Favorite

10 Places You Can’t Miss If It’s Your First Time in European
New Census Data Will Shake Up Alabama Politics
16 Top of Our Favorite Outdoor Clothing Brands
Fashionable Summer Accessories to Dress Up Your Travel Look
How Sleeping Less than 7 Hours a Night Can Lead to Weight Gain
-
 Entertainment2 years ago
Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’
-
 Sports2 years ago
China’s Historic Olympic Victory Sparks National Pride Amid Controversy
-
 Business2 years ago
Saudi Arabia’s Model for Sustainable Aviation Practices
-
 Business2 years ago
Recent Developments in Small Business Taxes
-
 Home Improvement2 years ago
Effective Drain Cleaning: A Key to a Healthy Plumbing System
-
 Politics2 years ago
Who was Ebrahim Raisi and his status in Iranian Politics?
-
 Sports2 years ago
Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m
-
 Business2 years ago
Carrectly: Revolutionizing Car Care in Chicago