Business
European Governments Expand Fuel Tax Cuts and Energy Support as Prices Surge

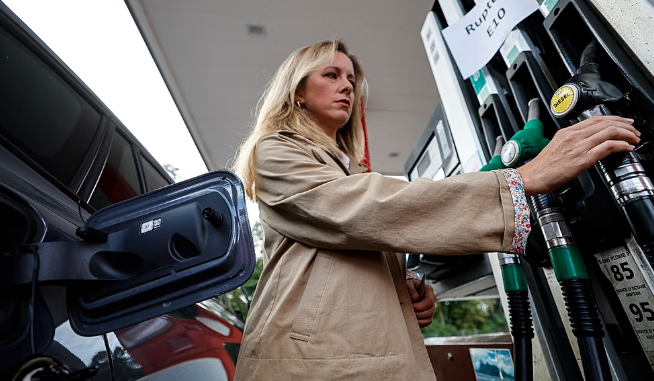
European governments are expanding fuel tax cuts, subsidies and energy measures as record petrol and diesel prices increase pressure on households and businesses across the region.
France, Germany and Spain are among the countries introducing or extending support as governments respond to disruptions linked to the wars in the Middle East and Ukraine. The European Union is also facing uncertainty over global diesel supplies amid possible US restrictions on exports.
The Organisation for Economic Co-operation and Development said seven of the 10 countries that have taken the largest number of measures to limit the economic impact of higher energy prices are EU members.
Europe was already facing energy challenges before the conflict involving Iran. Russia’s war in Ukraine disrupted supplies and contributed to sharp movements in European energy markets. The EU imports nearly all of the oil it consumes and about 85% of its natural gas, while imports account for 57% of the bloc’s overall energy needs, according to Eurostat.
Drivers are now facing particularly high diesel costs. Campaign group Transport & Environment estimates that EU motorists are spending an additional €203 million a day on diesel.
EU leaders have given member states temporary flexibility to provide state aid to households and energy-intensive sectors, including agriculture, transport and fishing. Governments have also been given limited flexibility under EU spending rules for investments aimed at strengthening energy security and reducing dependence on imported oil and gas.
European Commission President Ursula von der Leyen said higher energy prices and borrowing costs were putting pressure on households and businesses. She called for greater investment in domestic clean energy, including renewable power, nuclear energy and biomethane.
France has announced a €450 million package expanding assistance for fuel users and energy-intensive businesses. The government said 5.5 million workers who drive more than 30 kilometres on a round trip to work, or more than 8,000 kilometres a year for professional purposes, will qualify for €100 fuel payments through the end of the year.
Fuel subsidies for farmers, fishers and construction companies have also been extended. Energy vouchers ranging from €48 to €277 will be distributed three months earlier than planned to help 5.8 million households meet winter energy costs.
French President Emmanuel Macron has also asked the European Commission to consider relaxing some fuel quality requirements to increase diesel and kerosene production. He has proposed raising the EU limit for conventional biodiesel in standard diesel from 7% to 10%.
Germany has agreed to revive fuel tax cuts that expired at the end of June. From October 1 until the end of December, petrol and diesel prices will be reduced by 17 cents per litre, at a cost of €2.5 billion. Berlin also plans discussions with the oil industry over a possible fuel price cap from January.
Spain has extended fuel tax reductions introduced in March as part of a €5 billion support package. The current reduction is 5 cents per litre, with an automatic increase to 20 cents if annual fuel-price inflation exceeds 15%. Subsidies for transport firms, farmers, livestock producers and fishers have also been extended.
EU countries have also been drawing on strategic oil reserves after International Energy Agency members agreed to release 400 million barrels from emergency stockpiles.
At the same time, Europe continues to increase renewable energy production and shift industries toward electricity as it seeks to reduce dependence on imported fossil fuels.


Malta and Cyprus have secured places among the world’s 10 highest-ranked tax jurisdictions for people considering moving abroad, while Germany has been placed last in a new global comparison.
The ranking by Global Citizen Solutions (GCS) assesses 48 jurisdictions using 11 indicators grouped into tax burden, tax structure and investment migration. The investment migration category considers options available to people seeking residence or citizenship.
A higher score indicates more favourable conditions for internationally mobile individuals. Tax optimisation refers to the legal arrangement of finances to reduce tax liabilities.
Malta and Cyprus each scored 82 out of 100 for tax burden and 63 for tax structure. Malta received a score of 83 for investment migration, compared with 78 for Cyprus. Malta ranked sixth globally, while Cyprus came 10th.
GCS said the two countries achieved their positions through preferential tax regimes rather than low headline income tax rates. Their systems can provide favourable treatment for certain types of foreign income earned by people relocating to the countries.
Monaco, with a score of 68.6, Georgia at 68.3 and Bulgaria at 62.8, completed the top five European jurisdictions. After those countries, European scores fell below 60, with most placing outside the global top 20.
Germany ranked 48th and scored only 17 for tax structure. GCS identified the taxation of residents’ worldwide income, inheritance tax and exit tax as factors contributing to its position.
Denmark scored 30.4, Spain 36.9, France 37.7 and Norway 38.4. The United Kingdom was the next-lowest European jurisdiction, with a score of 50.9.
Italy recorded the highest score among Europe’s five largest economies at 56.9, placing ninth in Europe and 26th globally. Switzerland scored 58.2, followed by the Netherlands at 51.2. Turkey scored 56.9, Hungary 54.9, Sweden 54.1 and Ireland 53.1.
The separate tax burden measure covers personal income tax, capital gains tax on listed securities, wealth tax and inheritance tax. Monaco led Europe with 93, followed by Bulgaria at 92 and Andorra at 89. Malta and Cyprus both scored 82.
Tax structure focuses on foreign income and taxation affecting people who leave a country. Malta and Cyprus shared the highest European score of 63, while Germany recorded 17.
The report said tax rates and tax structures can operate independently, meaning a country with relatively low taxes may still have less favourable rules for foreign income or people relocating overseas.
Globally, the UAE ranked first with 82.7, followed by Antigua and Barbuda at 82.2, Paraguay at 77.2, Hong Kong at 76.9 and the Bahamas at 76.2.
The report also compared tax scores with quality-of-life rankings. Sweden, Germany, Denmark and Norway ranked highly for quality of life but much lower for tax optimisation.
Seven jurisdictions stood out for combining relatively favourable tax conditions with strong quality-of-life rankings: Malta, Cyprus, Portugal, Switzerland, Uruguay, Costa Rica and Mauritius.
The findings suggest that people considering relocation may assess tax structures alongside public services and wider living conditions, rather than focusing solely on headline tax rates.
European shares opened lower on Thursday as investors assessed recent swings in oil prices and rising US bond yields, with concerns about inflation and the economic outlook weighing on market sentiment.
Germany’s DAX fell 0.49% to 25,287.42, while France’s CAC 40 declined 0.37% to 8,093.68. The Euro Stoxx 50 was down 0.41% at 6,273.71 at the time of writing.
Asian markets were mixed earlier in the session. Japan’s Nikkei 225 gained 1.3% in morning trading to 65,883.41, helped by gains among some chipmakers as investor interest in artificial intelligence continued to support the technology sector.
Australia’s S&P/ASX 200 dropped 0.7% to 8,700.50. Hong Kong’s Hang Seng Index declined 0.5% to 24,715.95, while the Shanghai Composite fell 0.8% to 3,902.33. South Korean markets were closed for the Chuseok autumn harvest holiday.
Oil prices also moved lower. US crude fell 0.82% to $91.40 a barrel, while Brent crude, the international benchmark, declined 0.83% to $102.22.
Brent remains significantly above the roughly $72 a barrel level recorded before the war with Iran began. Investors remain concerned that the conflict could restrict oil supplies from the Middle East for an extended period.
US and Iranian officials, along with mediators, have continued discussions aimed at resolving the conflict, although no concrete agreement has emerged.
US bond yields weigh on Wall Street
US bond markets came under pressure overnight after stronger-than-expected economic data raised concerns that inflation could remain elevated.
The S&P 500 fell 0.8%, while the Dow Jones Industrial Average lost 352.10 points, or 0.7%, to 51,511.59. The Nasdaq Composite declined 308.24 points, or 1.1%, to 26,936.04.
The yield on the benchmark 10-year US Treasury note rose to 5.10% from 4.96%. It briefly approached 5.14% on Wednesday, a level not seen since 2007, before the global financial crisis sent borrowing costs sharply lower.
Higher Treasury yields can put pressure on equities and other assets by making borrowing more expensive and reducing the relative appeal of riskier investments. Recent increases have also reflected concerns over inflation, US government borrowing and the country’s rising debt burden.
A preliminary survey showed US business activity expanding at its fastest pace in more than five years, adding to concerns about price pressures.
The Federal Reserve raised its short-term interest rate last week for the first time in three years as inflation remained above its 2% target. Fed Governor Michael Barr said further increases “are likely to be needed” to bring inflation under control.
In currency markets, the dollar slipped to 157.94 yen from 158.30 yen. The euro was little changed at $1.1382, compared with $1.1388 previously.
The weak yen remains a concern for Japan because higher oil prices increase costs for the country’s import-dependent economy.
Britain’s largest banks have completed what the industry describes as the first transactions between rival lenders using tokenised deposits, marking a significant step in efforts to bring blockchain technology into the conventional banking system.
Lloyds, NatWest and Barclays carried out two remortgage transactions using tokenised deposits, while a separate group of three banks, including HSBC, completed a customer-to-customer payment designed to replicate a purchase through an online marketplace, industry body UK Finance said on Thursday.
Tokenised deposits are ordinary bank deposits recorded on a blockchain instead of a bank’s internal ledger. They retain the legal status and protections associated with conventional deposits, while allowing payments to be settled almost instantly and programmed to move when specified conditions are met.
The trials demonstrated how the technology could be used in real-world banking transactions. In the remortgage tests, funds were automatically released between banks after confirmation that a property transfer had been completed.
In the online marketplace trial, the buyer’s money was held until delivery was verified before being transferred to the seller. No actual goods changed hands during the test.
The ability to conduct transactions between different banks is central to the significance of the project. Banks have experimented with blockchain technology for more than a decade, but many initiatives operated on separate systems that could not communicate with each other.
The pilot, known as the Great British Tokenised Deposit project, was launched last year to test how tokenised deposits could operate across the banking sector.
Barclays, HSBC, Lloyds, Monzo, NatWest, Nationwide and Santander are participating in the project, which also has official backing.
The Bank of England has previously indicated that it would prefer banks to develop tokenised deposits rather than relying heavily on privately issued stablecoins. Stablecoins are digital tokens generally designed to maintain a fixed value against currencies such as the US dollar and are often issued outside the traditional banking system.
The participating banks now plan to establish a company and develop a common rulebook for the system. They also aim to issue three digital bonds during the first quarter of 2027, with the securities expected to be traded and settled using tokenised deposits.
The UK development comes as European authorities increase their focus on tokenised finance.
On Monday, the Eurosystem launched Pontes, a system allowing banks to settle transactions involving tokenised assets using central bank money. Thirteen institutions were ready to use the system immediately, while the European Central Bank said it would also invest some of its own funds in tokenised securities through the platform.
European central banks have also called for changes to the EU’s crypto framework, including tighter rules on stablecoins and greater powers to address tokens linked to foreign currencies.
The developments point to growing interest in using blockchain technology while keeping payments tied to regulated bank and central bank money.

Finland and Sweden Scramble Jets as Europe Raises Alert Over Russian Threats

European Governments Expand Fuel Tax Cuts and Energy Support as Prices Surge

Malta and Cyprus Rank Among Europe’s Most Tax-Friendly Destinations for Relocating Workers

European Stocks Slip as Oil Prices and US Bond Yields Keep Investors Cautious

US Navy Confirms Eight Suicide Attempts During Extended Carrier Deployment

UK Banks Complete First Interbank Transfers Using Tokenised Deposits

Europe Faces Higher Jet Fuel Costs Despite Supply Improving

More Europeans Take Up Sport, but Major Gaps Remain Across Countries

Alibaba Expands European Data Centres and Unveils New AI Chip

Congenital Infections Linked to Higher Risks of Autism and Intellectual Disability

Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’

China’s Historic Olympic Victory Sparks National Pride Amid Controversy

Saudi Arabia’s Model for Sustainable Aviation Practices

Recent Developments in Small Business Taxes

Effective Drain Cleaning: A Key to a Healthy Plumbing System

Who was Ebrahim Raisi and his status in Iranian Politics?

Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m

Carrectly: Revolutionizing Car Care in Chicago

Nobel Laureate Muhammad Yunus Proposed as Head of Bangladesh’s Interim Government Following Hasina’s Resignation

Chinese Hackers Infiltrate Major U.S. Telecom Firms in Possible National Security Breach
Sony WF-10XM4: Headphones Are Our Absolute Favorite

10 Places You Can’t Miss If It’s Your First Time in European
New Census Data Will Shake Up Alabama Politics
16 Top of Our Favorite Outdoor Clothing Brands
Fashionable Summer Accessories to Dress Up Your Travel Look
How Sleeping Less than 7 Hours a Night Can Lead to Weight Gain
-
 Entertainment2 years ago
Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’
-
 Sports2 years ago
China’s Historic Olympic Victory Sparks National Pride Amid Controversy
-
 Business2 years ago
Saudi Arabia’s Model for Sustainable Aviation Practices
-
 Business2 years ago
Recent Developments in Small Business Taxes
-
 Home Improvement2 years ago
Effective Drain Cleaning: A Key to a Healthy Plumbing System
-
 Politics2 years ago
Who was Ebrahim Raisi and his status in Iranian Politics?
-
 Sports2 years ago
Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m
-
 Business2 years ago
Carrectly: Revolutionizing Car Care in Chicago
You must be logged in to post a comment Login