Business
Corporate Income Tax Shares Vary Sharply Across Europe, OECD Data Shows

The contribution of corporate income tax (CIT) to government revenues and economic output differs significantly across Europe, highlighting the impact of economic structure and national tax policies, according to new data from the OECD.
Corporate income tax, levied on companies’ net income, profits and capital gains, accounts for roughly 4% of GDP across OECD members. But within Europe, the share of CIT in total tax revenues in 2023 ranged from as low as 4.2% in Latvia to as high as 28.3% in Norway.
Norway and Ireland Lead the Rankings
Norway tops the list, with corporate taxes accounting for more than a quarter of its overall tax revenues, thanks largely to its highly profitable oil and gas sector. Ireland follows with 21.7%, while Czechia ranks third at 13.9%. Turkey (12.8%) and the Netherlands (12.7%) round out the top five.
By contrast, many European economies fall closer to the average of 9.8%. Among the Nordic countries, Iceland (9.4%), Denmark (8.7%), Sweden (8.6%) and Finland (6.8%) are much nearer to the regional norm.
“Norway, which has a more moderate corporate tax rate compared to other European countries, has notably high CIT revenues due to the presence of profitable sectors such as oil and gas,” said Cristina Enache, economist at Tax Foundation Europe.
Divergence Among Major Economies
Europe’s largest economies show a striking divergence. The UK records the highest share of CIT among the top five, at 10.1%. France sits at the other extreme with just 5.3%, placing it near the bottom of the European rankings. Germany (6.1%), Italy (6.5%), and Spain (7.9%) all fall below the average, reflecting what analysts describe as diversified economies that rely more heavily on income and consumption taxes.
Why the Gap Exists
Experts attribute these differences to variations in economic structure, corporate profitability, and national tax regimes. Some governments, such as Ireland and Lithuania, use lower corporate tax rates to attract investment. Others, like Germany and the UK, apply generous allowances and deductions that reduce effective CIT collections.
In Estonia and Latvia, only distributed earnings are taxed, allowing firms to defer payments if profits are reinvested. “This policy encourages investment and entrepreneurship but results in lower immediate CIT revenues,” Enache explained.
CIT as a Share of GDP
Measured against GDP, Norway again leads with CIT equivalent to 11.7% of output—more than triple the European average of 3.5%. Luxembourg (5.0%), the Netherlands (4.9%), Czechia (4.7%) and Ireland (4.7%) also rank highly. At the bottom, Latvia (1.3%) and Estonia (1.9%) collect the least relative to GDP.
Tax rates themselves are less variable, clustering between 20% and 25% across most of Europe. Hungary applies the lowest rate at 9%, while Malta has the highest at 35%. Norway, despite being the top revenue generator, applies a relatively modest 22% rate.
Analysts say the contrast between countries like Norway and Estonia illustrates broader policy choices: some governments leverage corporate taxes to capture resource rents, while others prioritise investment-friendly frameworks.
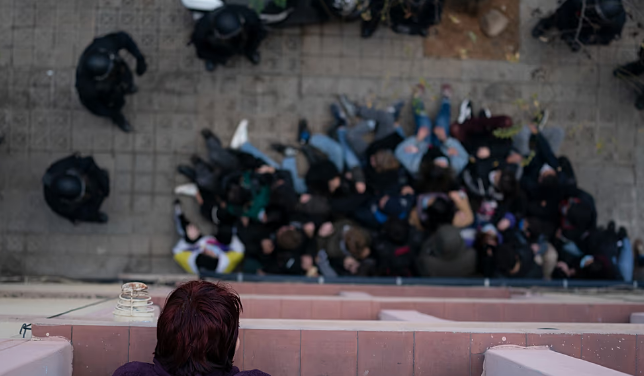
A lack of transparency over property ownership is making it difficult to determine how much housing is controlled by large landlords in Spain, even as major investors continue to make significant purchases across the country.
Public data does not provide a complete picture of residential properties owned by companies or individuals with more than 10 homes or 1,500 square metres of residential space. Although the national cadastre holds ownership records, the information is anonymised, limiting efforts to identify the largest landlords and track changes in their portfolios.
Rental-market data can sometimes be obtained through transparency requests to Spain’s autonomous communities, which oversee tenant deposit records. However, such information excludes owner-occupied and vacant properties as well as other categories of housing, making it difficult to establish the full scale of corporate ownership in real time.
Property transactions announced by companies during 2026 nevertheless show continued activity among major investors. The biggest deal so far involved Fidere, a group of listed real estate investment trusts focused on public and rental housing. Canadian investment group Brookfield bought Fidere from Blackstone in March for €1.05 billion, acquiring 47 buildings containing more than 5,000 rental homes.
In May, Azora agreed to acquire 1,200 rental homes in the Barcelona metropolitan area from Patrizia for more than €350 million. Patrizia had purchased the properties from BeCorp in 2022 for about €600 million.
Other deals involve homes that have yet to be completed. Barings is due to acquire 305 affordable homes from Aurora Homes in Madrid’s Los Cerros development for more than €70 million, with completion expected in 2029. It is also buying 188 homes in Valdebebas for more than €56 million from Grupo Ferrocarril.
Public authorities are also granting concessions on public land to private housing companies, sometimes for periods of 45 to 75 years. This is taking place while Spain’s social rental housing stock remains at just 1.72%, compared with an estimated European average of 8% to 9%.
Culmia, controlled by US investment firm Oaktree, has been involved in several such transactions. In 2025, it transferred a Madrid Plan Vive social housing portfolio to German asset manager DWS through a €255 million transaction. MEAG has also acquired a 50% stake from Culmia in a portfolio containing more than 1,700 homes across Madrid and Valencia.
At the same time, Spain’s wider housing market is showing signs of slower sales growth. Cushman & Wakefield reported a 3.51% annual decline in transactions through May 2026, to about 286,000. BBVA Research expects transactions to fall 7.3% this year before rising 0.6% in 2027.
Despite weaker sales, investment in rental housing has surged. Cushman & Wakefield recorded €2.934 billion in transactions involving large landlords and investment funds during the first half of 2026, a 376% increase from a year earlier.
The figures reflect different parts of the market, as a small number of large portfolio purchases can sharply increase investment volumes without indicating an equivalent rise in the number of individual home sales.
Housing has also become Spain’s leading public concern. According to the September CIS barometer, 37.5% of respondents identified housing as the country’s main problem, ahead of economic issues at 21.6% and immigration at 19.7%.
Oxfam France has called for a major reform of the country’s Dutreil tax pact, arguing that changes to the scheme could generate billions of euros for public finances by increasing taxation on the largest business inheritances.
The proposal comes as France begins preparations for its 2027 budget amid mounting pressure to reduce the deficit and contain rising public debt. In a report published on Tuesday, September 22, Oxfam identified large inheritances as a potential source of additional government revenue.
The Dutreil pact, introduced in 2003 under then Trade and Crafts Minister Renaud Dutreil, provides a 75% exemption from gift and inheritance taxes when eligible businesses are transferred to heirs. The scheme was designed to help families pass businesses to the next generation without being forced to sell them to meet tax liabilities.
Beneficiaries must meet conditions including retaining their shares for a specified period and maintaining certain business activities. France’s 2026 finance law tightened some of the rules by extending the required holding period and excluding certain assets that are not directly related to business operations.
Oxfam said transfers made under the Dutreil pact have represented almost €3 billion in annual tax expenditure on average over the past four years, with the figure reaching €5.5 billion in 2024, citing the French Court of Audit.
The organisation estimates that transferring the wealth of French billionaires aged over 70 through the scheme could result in more than €111 billion in lost public revenue over the next 30 years if current rules remain unchanged. Oxfam stressed that this is a projection and not an amount the government would automatically collect if the scheme were abolished.
The group argues that the tax benefit is particularly concentrated among the wealthiest recipients. According to its calculations, the 110 most advantaged beneficiaries, representing about 1% of recipients, saved an average of €30 million each in tax in 2024. Meanwhile, half of the least advantaged beneficiaries saved less than €40,000 on average.
Oxfam proposes limiting the Dutreil exemption to €1 million per beneficiary. It estimates that about 90% of current beneficiaries would remain unaffected by the proposed cap, while the state could raise more than €3 billion annually.
The debate is expected to form part of discussions surrounding France’s 2027 finance bill. Any reform would need to balance additional tax revenue against the original purpose of the Dutreil pact, which is to facilitate the transfer of family businesses.
Layla Abdelke Yakoub, Oxfam France’s Advocacy Manager for Tax Justice and Inequality, said Prime Minister Sébastien Lecornu had indicated that the government would not change the Dutreil pact.
Oxfam said it hoped the government would reconsider its position and called for the largest fortunes to make a greater contribution to France’s fiscal effort.
Volkswagen has been removed from the Euro Stoxx 50, the benchmark index of major companies listed in the eurozone, adding pressure on Europe’s biggest carmaker just days after it issued a major profit warning.
The change took effect when European markets opened on Monday following an annual review by index provider Stoxx. Volkswagen was replaced by Finnish telecoms group Nokia, while French utility Engie joined the index. Dutch information services company Wolters Kluwer was also removed.
Volkswagen’s departure from the index was based on its falling free-float market value rather than a specific assessment of its business performance. The Euro Stoxx 50 is weighted according to the market value of shares available for public trading, meaning Volkswagen no longer met the required threshold.
The move could still affect the company’s shares because investment funds that track the index are required to adjust their portfolios. That can result in additional selling pressure on stocks removed from the benchmark.
Volkswagen shares have fallen almost 30% since the beginning of the year and were down more than 6% from last Monday’s opening. The shares were trading at around €76.
The index change came shortly after Volkswagen issued a warning about its financial outlook. On Friday, the company said one-off charges of about €10 billion would significantly reduce its 2026 earnings.
Volkswagen lowered its operating margin forecast to no more than 1%, compared with its previous guidance of between 4% and 5.5%. Analysts had been expecting a margin of about 4.1%.
More than €6 billion of the charges are linked to a writedown at Porsche, in which Volkswagen owns a 75.4% stake. Porsche has faced weaker demand in China and the impact of US tariffs on its business. Its operating margin was only 1.1% last year.
Volkswagen also expects more than €2 billion in charges related to expanded early retirement programmes, impairments in China and the planned sale of its Osnabrück manufacturing subsidiary.
The company cited a worsening market environment, particularly in China, as well as a faster shift in consumer demand toward battery-electric vehicles.
The warning followed a restructuring agreement announced two weeks earlier that would double planned job reductions to 100,000 and reduce Volkswagen’s model range by half.
Volkswagen said its underlying operating margin, excluding the one-off charges, was around 4%. It also maintained its forecasts for cash flow and liquidity.
Deutsche Bank said the headline figures overstated the deterioration in Volkswagen’s underlying business, although it expects the restructuring process to remain costly and complex.
Volkswagen is due to report its third-quarter results on October 29, when investors will receive a fuller picture of the company’s financial performance and restructuring plans.

Congenital Infections Linked to Higher Risks of Autism and Intellectual Disability

Spain’s Housing Market Faces Growing Pressure as Big Landlords Expand

Oxfam Calls for Reform of France’s Dutreil Pact to Raise Billions

Volkswagen Removed From Euro Stoxx 50 After Profit Warning

French Diesel Prices Hit Record as Middle East War Drives EU Fuel Costs Higher

Volvo Cars Names Škoda Chief Klaus Zellmer as Next CEO


US Embassies Warn Americans of Rapidly Escalating Middle East Conflict

Baby Essentials Cost Thousands of Euros Across Europe, Study Finds

Global Survey Finds Growing Concern Over AI-Driven Job Losses

Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’

China’s Historic Olympic Victory Sparks National Pride Amid Controversy

Saudi Arabia’s Model for Sustainable Aviation Practices

Recent Developments in Small Business Taxes

Effective Drain Cleaning: A Key to a Healthy Plumbing System

Who was Ebrahim Raisi and his status in Iranian Politics?

Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m

Carrectly: Revolutionizing Car Care in Chicago

Nobel Laureate Muhammad Yunus Proposed as Head of Bangladesh’s Interim Government Following Hasina’s Resignation

Chinese Hackers Infiltrate Major U.S. Telecom Firms in Possible National Security Breach
Sony WF-10XM4: Headphones Are Our Absolute Favorite

10 Places You Can’t Miss If It’s Your First Time in European
New Census Data Will Shake Up Alabama Politics
16 Top of Our Favorite Outdoor Clothing Brands
Fashionable Summer Accessories to Dress Up Your Travel Look
How Sleeping Less than 7 Hours a Night Can Lead to Weight Gain
-
 Entertainment2 years ago
Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’
-
 Sports2 years ago
China’s Historic Olympic Victory Sparks National Pride Amid Controversy
-
 Business2 years ago
Saudi Arabia’s Model for Sustainable Aviation Practices
-
 Business2 years ago
Recent Developments in Small Business Taxes
-
 Home Improvement2 years ago
Effective Drain Cleaning: A Key to a Healthy Plumbing System
-
 Politics2 years ago
Who was Ebrahim Raisi and his status in Iranian Politics?
-
 Sports2 years ago
Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m
-
 Business2 years ago
Carrectly: Revolutionizing Car Care in Chicago