Business
Oil Prices Rise Amid Middle East Tensions and OPEC+ Policy Delay





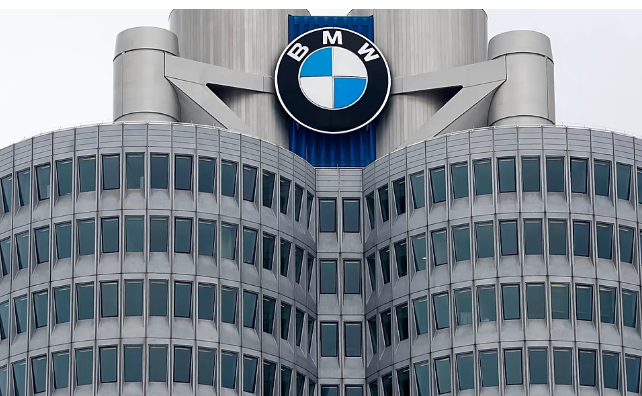
BMW reported a decline in third-quarter profits on Wednesday, a day after issuing its second profit warning of the year as mounting competition from Chinese carmakers and restructuring costs put pressure on the German manufacturer’s business.
The company’s pre-tax profit fell 11% in the three months to September, while net profit dropped around 15% to €1.45 billion. Revenue declined almost 6% to €30.45 billion, BMW said.
The latest warning, announced on Tuesday, followed higher restructuring expenses, including the planned elimination of around 8,000 jobs in Germany. BMW said these costs could push its core automotive division close to break-even, or into an operating loss, for the full year.
The operating margin in the car division fell to 3.4% in the third quarter, compared with 5.2% in the same period last year. BMW now expects the division’s full-year operating margin to range between minus 0.5% and plus 0.5%, a sharp reduction from its previous forecast of 1% to 3%.
BMW chief executive Milan Nedeljkovic said the company needed to respond quickly to changes across the automotive industry.
“Current developments in our industry call for decisiveness and swift implementation,” he said. “We will therefore specifically intensify and accelerate structural measures.”
The pressure reflects wider challenges facing German manufacturers, including Mercedes-Benz and Volkswagen, which are also reducing costs and jobs. Chinese carmakers have gained ground in their domestic market with competitively priced vehicles and advanced technology, while expanding their presence in Europe.
BMW’s difficulties have been particularly pronounced in China, traditionally one of its most important markets. Vehicle deliveries there fell 24.8% in the third quarter, extending a decline that has already taken sales to their lowest level since 2017 last year.
The drop in China contributed to a 6.3% decline in BMW’s global deliveries during the quarter. Sales moved in the opposite direction in other major markets, rising 2.6% in Europe and 2.5% in the United States.
The group, which owns the BMW, Mini and Rolls-Royce brands, is seeking to regain ground in China by shifting more of the supply chain for vehicles made there to local suppliers. The strategy is intended to improve competitiveness and respond more closely to customer demand in the market.
The latest results add to concerns about the outlook for Germany’s automotive industry, which faces pressure from weaker demand, high production costs and the rapid expansion of Chinese competitors.
Despite the profit warning and weaker quarterly performance, BMW shares rose around 2% from Tuesday’s closing level by 11 a.m. Central European Time on Wednesday.
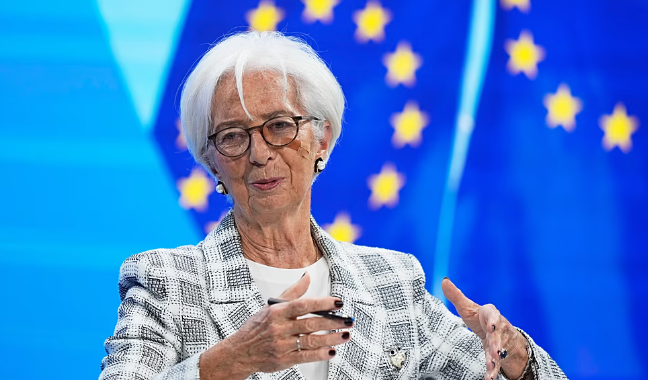
Eurozone governments have until Friday, 6 November, to nominate candidates to succeed European Central Bank (ECB) President Christine Lagarde, with finance ministers scheduled to review the submissions at a meeting on 9 November.
The appointment process began after Lagarde informed European Council President António Costa last week that she intended to leave the post on 7 February 2027, almost nine months before the end of her eight-year term.
A Eurogroup spokesperson told Euronews that the Council of the European Union had initiated the procedure to appoint her successor. The ECB Executive Board is appointed by the European Council, which makes its decision based on a recommendation from the Council of the EU.
Eurogroup President and Greek Finance Minister Kyriakos Pierrakakis has asked eurozone members to submit nominations by Friday. The Eurogroup will then assess the candidates at its 9 November meeting.
A nominee must secure support from at least 16 of the 21 eurozone countries, representing at least 65 per cent of the bloc’s population. EU leaders will make the final appointment after receiving opinions from the European Parliament and the ECB’s Governing Council.
Lagarde announced her early departure last Thursday, saying she wanted greater freedom to speak about issues beyond monetary policy.
“I don’t think that I can remain neutral,” she told reporters in Frankfurt. “I’m interested in the truth, and I see the truth being very often damaged, contradicted by misrepresentation.”
She did not say whether she would support a candidate in France’s presidential election in April 2027. Her decision to leave early has fuelled speculation about the timing of the succession, allowing French President Emmanuel Macron and German Chancellor Friedrich Merz to influence the appointment before the election.
Lagarde has promised continuity at the central bank and is expected to chair two more interest-rate meetings, in December and February. The ECB kept its deposit rate at 2.5 per cent at its latest meeting.
Two candidates have emerged as leading contenders. Spain has backed Pablo Hernández de Cos, general manager of the Bank for International Settlements and former governor of the Bank of Spain. Prime Minister Pedro Sánchez publicly endorsed him in September, while opposition leader Alberto Núñez Feijóo has also expressed support.
The Netherlands has backed former central bank governor Klaas Knot, who led the institution for 14 years until 2025. Prime Minister Rob Jetten described him as a “perfect fit” for many countries.
Other names mentioned in the race include former Bank of France governor François Villeroy de Galhau and Bundesbank President Joachim Nagel.
The negotiations are expected to extend beyond the presidency. ECB Executive Board positions held by Germany’s Isabel Schnabel and Ireland’s chief economist Philip Lane are also due to become vacant in the coming months. With several senior posts changing hands, governments are expected to negotiate over the appointments as part of a wider package.
Ryanair reported a 15% decline in first-half net profit as rising jet fuel costs and lower ticket prices outweighed an increase in passenger numbers, highlighting the pressure facing European airlines ahead of another potentially expensive year.
The Irish airline recorded a net profit of €2.15 billion for the six months from April to September 2026, compared with the same period a year earlier. Diluted earnings per share fell 14% to €2.05.
Revenue increased by 3% to €10.08 billion, while passenger numbers rose 6% to 125.8 million. However, average fares declined by 4%, limiting the benefit of higher traffic. Operating costs climbed 10% to €7.69 billion.
Ryanair said the conflict in the Middle East had made consumers more cautious and encouraged them to book flights closer to departure dates. The airline also faced higher fuel expenses as unhedged jet fuel prices doubled.
The results reflect only part of the increase in fuel prices because Ryanair has secured contracts covering 80% of its fuel requirements for the financial year ending March 2027. These arrangements have helped protect the company from market volatility, but the remaining 20% of its requirements has been exposed to higher prices.
Fuel costs expected to rise sharply
Ryanair estimates that its fuel bill could increase by around €2 billion in the financial year ending March 2028, based on current forward prices.
“Unless there is a swift resolution of the Middle East conflict, we expect jet-fuel prices to remain elevated well into 2027,” chief executive Michael O’Leary said.
O’Leary also warned that the airline’s existing lower-cost fuel hedges would expire ahead of summer 2027, potentially leaving European carriers facing significantly higher expenses.
He previously forecast that European airfares could increase by as much as 20% next year. However, Ryanair expects higher ticket prices and capacity reductions by competing airlines to be insufficient to offset the full increase in fuel costs.
The company is reviewing measures to control spending, including temporary pay freezes, lower crew-to-passenger ratios and wider use of artificial intelligence across operational and support functions.
Ryanair also announced an €800 million share buyback programme, due to begin in February 2027 and run for approximately 10 months, subject to market conditions.
Demand for October to December remains strong, with fares modestly above last year’s levels. However, the growing trend towards late bookings makes future revenue harder to assess.
The airline declined to provide a full-year profit forecast, citing uncertainty surrounding geopolitical conflicts, fuel prices, economic conditions and disruption to European air traffic control.
In September, Ryanair announced cuts to its winter schedule to reduce exposure to unhedged fuel costs. It also lowered its full-year passenger target from 216 million to 214 million.
Ryanair shares rose 2% in Dublin during early trading on Monday.

Experts Call for Stricter Fireworks Rules as Injuries Rise Across Europe

European Campaigners Demand Pause on Large Data Centre Projects Amid Growing Local Opposition

One in Four Teenagers Worldwide Does No Weekly Exercise, Study Finds

US Midterm Results Put Data Centre Expansion Under Pressure as Democrats Win Key States

BMW Profits Fall as Chinese Competition Forces Deeper Cost Cuts

Eurozone Opens Race to Replace ECB President Christine Lagarde

Health Groups Urge WHO to Tighten Drinking Water Nitrate Limits Over Cancer Risks

Anthropic Revenue Jumps to $17 Billion as AI Spending Drives Up Costs Ahead of Nasdaq IPO

Argentina’s Milei Courts AI Data Centre Investors With Tax Incentives and Light Regulation

Ryanair First-Half Profit Falls 15% as Higher Fuel Costs and Lower Fares Hit Earnings

Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’

China’s Historic Olympic Victory Sparks National Pride Amid Controversy

Saudi Arabia’s Model for Sustainable Aviation Practices

Recent Developments in Small Business Taxes

Effective Drain Cleaning: A Key to a Healthy Plumbing System

Who was Ebrahim Raisi and his status in Iranian Politics?

Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m

Carrectly: Revolutionizing Car Care in Chicago

Nobel Laureate Muhammad Yunus Proposed as Head of Bangladesh’s Interim Government Following Hasina’s Resignation

Chinese Hackers Infiltrate Major U.S. Telecom Firms in Possible National Security Breach
Sony WF-10XM4: Headphones Are Our Absolute Favorite

10 Places You Can’t Miss If It’s Your First Time in European
New Census Data Will Shake Up Alabama Politics
16 Top of Our Favorite Outdoor Clothing Brands
Fashionable Summer Accessories to Dress Up Your Travel Look
How Sleeping Less than 7 Hours a Night Can Lead to Weight Gain
-
 Entertainment2 years ago
Meta Acquires Tilda Swinton VR Doc ‘Impulse: Playing With Reality’
-
 Sports2 years ago
China’s Historic Olympic Victory Sparks National Pride Amid Controversy
-
 Business2 years ago
Saudi Arabia’s Model for Sustainable Aviation Practices
-
 Business2 years ago
Recent Developments in Small Business Taxes
-
 Home Improvement2 years ago
Effective Drain Cleaning: A Key to a Healthy Plumbing System
-
 Politics2 years ago
Who was Ebrahim Raisi and his status in Iranian Politics?
-
 Sports2 years ago
Keely Hodgkinson Wins Britain’s First Athletics Gold at Paris Olympics in 800m
-
 Business2 years ago
Carrectly: Revolutionizing Car Care in Chicago